Executive Summary
Electrification is advancing significantly in automotive markets, particularly in Europe, where electric vehicle (EV) registrations hit 31% in 2025, an increase from 25% in 2023. Leading countries like Norway and the Netherlands are at the forefront of this transition. A survey by the WBCSD revealed that 92% of leaders believe sustainability offers a competitive edge, with 89% increasing investment in this transition.
As vehicles become greener, the carbon challenge shifts upstream to embedded emissions in materials like steel, aluminum, batteries, and plastics. Achieving carbon neutrality now requires a broader focus on procurement and the value chain.
To reach carbon neutrality, two strategies must work in tandem: supply chain decarbonization and circularity. Market complexity, regulatory uncertainty, and alignment challenges hinder rapid progress. This briefing reflects insights from the Business Breakthrough Barometer and highlights mechanisms to enhance decarbonization in the automotive sector.
The Carbon Challenge Is Migrating Upstream
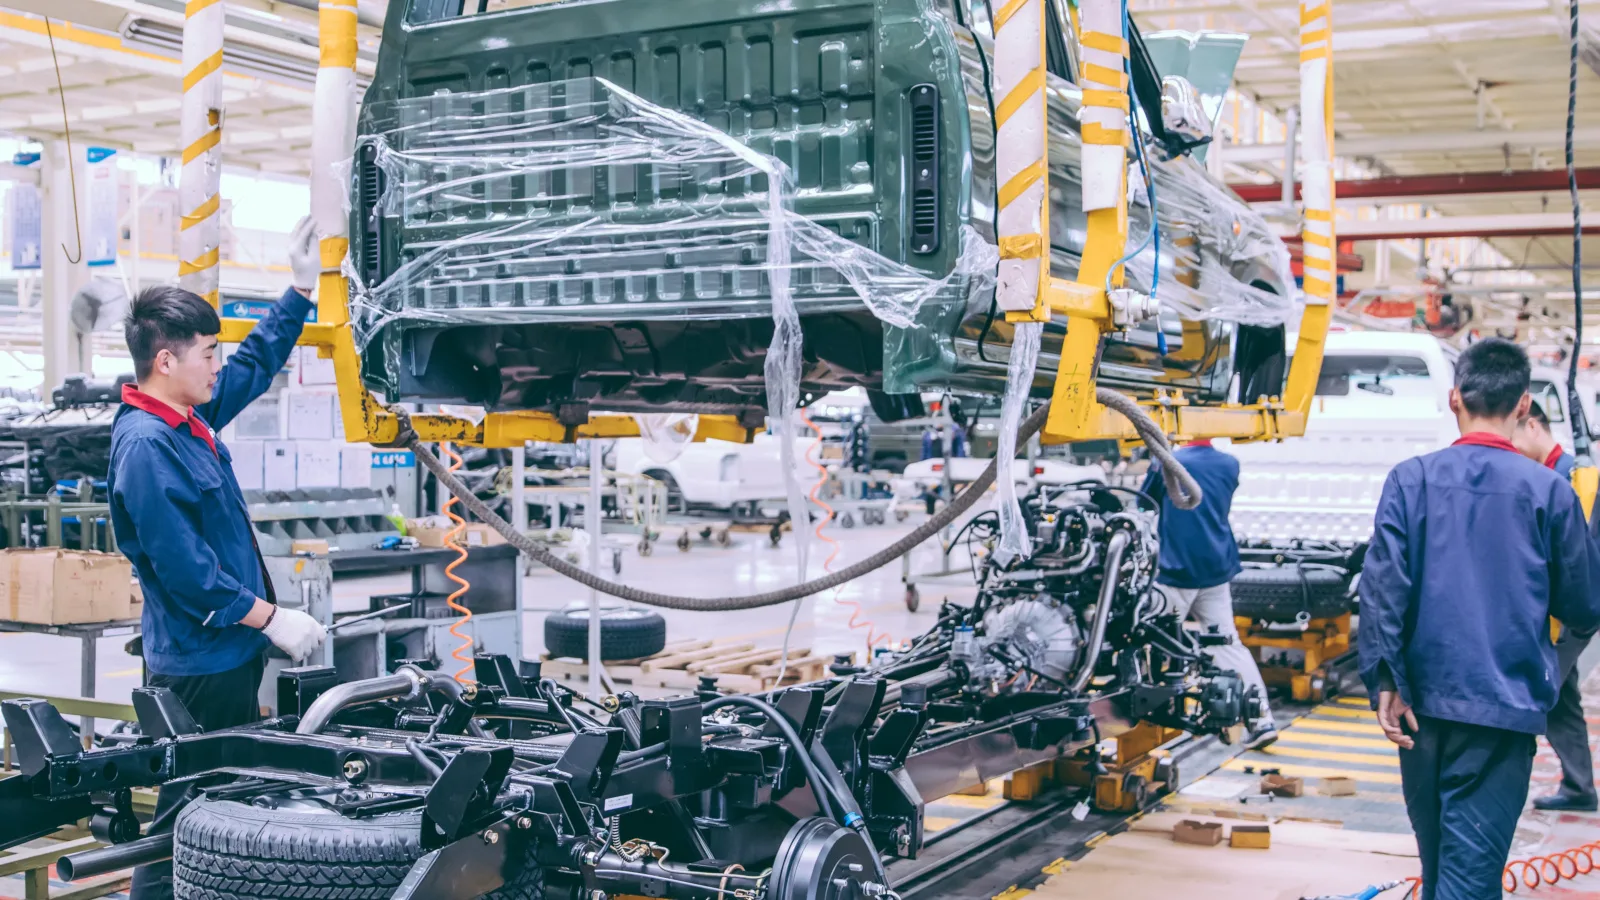
As the grid becomes greener, the emissions from manufacturing, especially in battery cells, are increasingly significant, comprising up to 31% of a vehicle’s lifecycle footprint. Research indicates that emissions from these hotspots could decline by 69-91% by 2050 through efficient practices, but these must be implemented quickly.
In light-duty vehicles, supply chain emissions currently account for 20% of the lifecycle footprint. As electrification expands, this could rise to 60-70%, underscoring the need for upstream decarbonization.
Two Levers, Pulled in Concert
Supply Chain Decarbonization: This involves reducing embedded carbon through advanced manufacturing techniques.
Circularity: This focuses on keeping materials like steel and batteries in continuous use through recycling and efficient design.
For optimal results, both approaches must be integrated; relying solely on one could limit effectiveness due to material limits and cost competitiveness.
Steel as the Proving Ground
Steel presents a significant and immediate opportunity for emissions reduction. The IEA emphasizes a 25% reduction by 2030, with automotive as a major consumer driving procurement changes. Recent data shows a 22% year-over-year increase in low-emissions steel contracts, primarily fueled by automotive demand.
Efforts to Address Market Gaps
However, the transition faces challenges:
- Regulatory Uncertainty: Existing policies often lag behind, hindering investment clarity.
- Lack of Harmonization: A unified definition of “low-carbon” materials is necessary for confidence in transactions.
- Cost Premium: Variations in green pricing can create disparities.
- Supply-Demand Gaps: The concentration of demand from automakers poses challenges for broader sector adoption.
These gaps are being addressed through collective action, with businesses forming coalitions to secure future supplies and drive standards.
Enabling Market and Regulatory Mechanisms
To close these gaps, existing mechanisms can be utilized:
- Fleet Emissions CO2 Compliance: Manufacturers could meet part of CO2 targets through low-carbon material credits.
- Market-Based Mechanisms: Exploring traceability and accountability standards can facilitate transactions involving low-carbon materials.
- Carbon Pricing: Establishing a predictable carbon price can be instrumental in bridging the business case gap.
Next Steps
WBCSD calls upon regulators and businesses to capitalize on emerging opportunities. Future analyses will delve deeper into materials and circularity aspects, emphasizing the need for collective, sustained efforts toward supply chain decarbonization.
Achieving carbon neutrality necessitates collaboration across the value chain backed by stable policy support.