This week marks the fundraising initiative for Naked Capitalism. We are grateful to the 1,317 donors who have supported our mission to fight corruption and predatory behaviors, especially within the financial sector. We invite you to contribute via our donation page, where you can learn how to donate using various methods including checks, credit or debit cards, PayPal, Clover, or Wise. You can also read about the rationale behind this fundraiser, our achievements over the past year, and our current goal: enhanced original reporting.
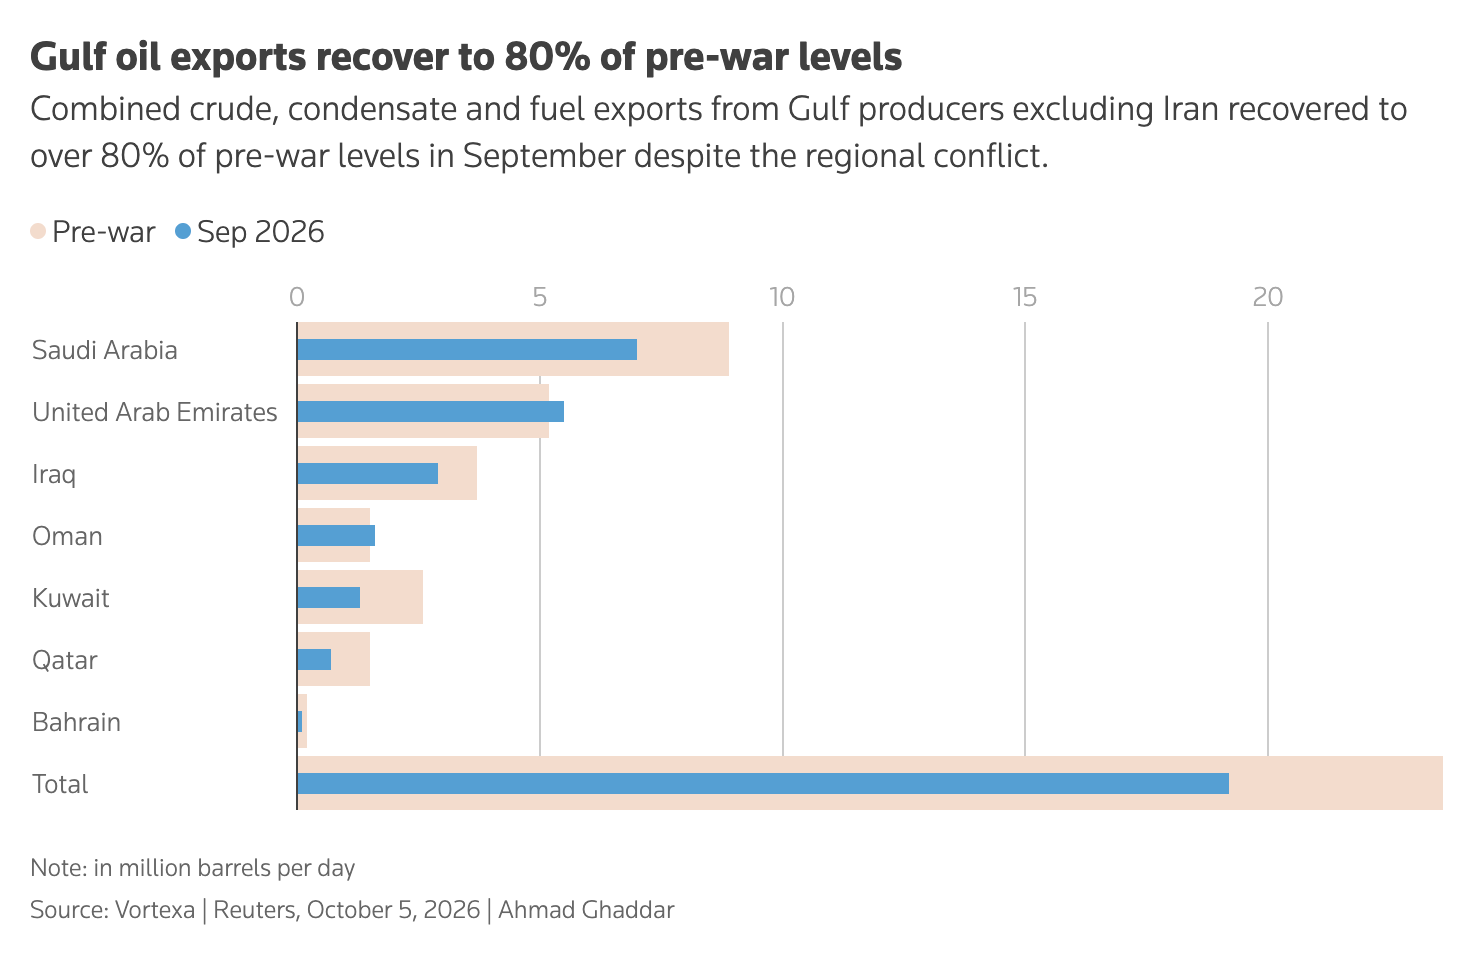
This article provides an updated assessment of oil exports in the Persian Gulf for September, revealing that they are currently about 80% of pre-war levels, according to studies from both Reuters and Standard Chartered. While this represents a notable increase from previous months, it’s crucial to recognize that the current situation still mirrors an energy hardship. Both government and private sector inventories are being depleted rapidly. The U.S. has announced a release of 40 million barrels from its Strategic Petroleum Reserve, reflecting previously planned drawdowns. Additionally, the U.S. has pressured European nations to utilize their diesel reserves. Overall, this is not a sign of stabilization, and even with increased exports from the Gulf, the underlying issues remain the same; the situation may only be delaying an impending crisis marked by price surges, shortages, or rationing.
The figures provided by Reuters and Standard Chartered even exceed some cautious estimates circulating on Twitter, which suggested a range of 8 to 12 million barrels per day. However, the higher estimates may align with Standard Chartered’s analysis, which reports slightly lower figures than Reuters while still indicating that exports are at 80% of the former normal levels, which suggests consistency in definitions or measurements across both datasets.
Notably, Standard Chartered considers all oil exports, not just those that transit through the Strait of Hormuz, which has been a major point of discussion. They indicate that while those exports are indeed lower at about 60% of former levels, efforts to reroute shipments have aided exporters in maintaining overall export volumes.
That said, I find it challenging to comprehend the reported levels of Saudi exports, as these do not seem to account for significant damage to the east-west pipeline and the operational status of the port at Yanbu. I anticipate that this analysis will spark further discussion and possibly critique.
Moreover, the Standard Chartered evaluation emphasizes a point raised earlier: the high costs associated with these exports. I previously quoted Trita Parsi’s remarks about a conversation involving oil expert Rory Johnson and Michelle Brohard, which align with insights from Iranian officials. This information is noteworthy as it underscores the substantial costs that both the U.S. and Gulf States incur, suggesting that such an operational setup may not be sustainable.
🛢️ Countries getting crude out of the Strait of Hormuz may be paying Iran a toll for safe passage, possibly 10% to 20% of each cargo, Kpler head of policy and geopolitical risk Michelle Brohard said, specifying it was “just my speculation.”
Brohard said the current setup is “unsustainable,” with costly US Navy escorts as well as a “hefty fee to Iran.” As such, exporters are racing to move “as much as possible, as quickly as possible before the war restarts,” she told energy analyst Rory Johnston.
@Rory_Johnston | Full video on YouTube. Link in reply.
— Drop Site (@DropSiteNews) October 3, 2026
The key points from the Reuters story, Gulf oil flows rise to average 81% of pre-war rate in September, data shows:
Gulf oil flows excluding Iran surged to over 81% of pre-war levels in September, data showed, led by a recovery in Saudi exports despite attacks on the kingdom’s oil infrastructure and escalating Iranian attacks on regional shipping, while Iranian exports fell to zero due to a US blockade…..

It is important to note that the reported figures are based on Kpler data, a source that has faced skepticism, including from TankerTrackers. However, Iranian sources do not contest that a larger volume of oil and products is leaving the country. Thus, the debate primarily revolves around the extent of the increase rather than its existence.
As previously mentioned, recent military actions have largely focused on Saudi efforts, aided by their allies in Yemen, to regain territory previously seized by Ansar Allah. The Saudis have deployed roughly 100 aircraft in these operations. Nevertheless, as Robert Pape cautioned, airstrikes alone do not determine the outcome of conflicts, and the Saudi military is often viewed as ineffective, especially regarding ground operations.
A recent gathering of the Mecca Alliance in Riyadh underscores their purely defensive nature. Although the Saudis secured additional commitments from Pakistan and Turkey, it is assumed that their involvement will remain limited to securing Saudi interests rather than actively participating in offensives in Yemen.
Turkiye and Pakistan have agreed to a rapid military deployment under the Mecca defence pact to bolster Saudi Arabia’s security following Houthi threats to Mecca and Medina.
Al Jazeera’s @osamabinjavaid reports. https://t.co/TAxEZ8sSeQ
— Al Jazeera English (@AJEnglish) October 6, 2026
Providing troops for defensive purposes would allow the Saudis to allocate their resources more freely in Yemen.
There are differing opinions on the evolving Saudi campaign in Yemen:
The Saudi offensive is only just beginning.
Today, hundreds of drones, dozens of helicopters and a large combat aviation force were used against Houthi positions, which lost ground in open terrain along the coast.
Anyone expecting the Saudis to act as they did in the Yemeni civil war, where they were defeated, is mistaken. This will be an extremely hard war for the Houthis, who will retaliate against the Saudi and Emirati oil industries.
The central question comes down to two points:
1. How far are the Saudi and Emirati industries willing to overlook the economic damage? Yes, the bill will reach the Emirates as well before long, since their proxies are already fully engaged and moving into the front lines.2. Inevitably, Iran will have to act more decisively. Once the Saudis and Emiratis are ignoring the damage to their own economies, a not-so-distant scenario may emerge where Trump resumes the war without regard for Iranian counteractions against GCC industries.
That is the impending scenario if the war in Yemen keeps escalating.
A more brutal resurgence of Yemen’s civil war will carry far greater consequences than in previous years.Optimists argue that Iran’s current economic plight limits its capacity to support the Houthis, portraying this as a prime opportunity.
However, the Yemeni forces still possess ample military supplies to sustain months of conflict, even with substantial backing from Saudi allies.
This conflict is rapidly evolving, now characterized mainly by drones and rapid vehicles on the battlefield, alongside missile exchanges targeting each other’s economies and logistics.
https://t.co/P6RN2eyQzB
— Patricia Marins (@pati_marins64) October 6, 2026
If you unfollow Al Jazeera and other US-oriented media outlets and follow alternative media instead, you do yourself a favor.
— Seyed Mohammad Marandi (@s_m_marandi) October 6, 2026
By Alex Kimani, a seasoned finance writer, investor, engineer, and researcher for Safehaven.com. Originally published at OilPrice
- Gulf oil exports rebounded to approximately 16.5 million barrels per day (bpd) in September, nearing pre-war volumes, despite only 60% of those barrels passing through Hormuz compared to 83% prior to the conflict.
- Exporters have adapted by utilizing pipelines, bypassing ports, and employing extensive ship-to-ship transfers; nonetheless, these methods come with greater inefficiencies and costs, further straining the system.
- Iran’s capacity to disrupt regional oil exports has diminished, while its own seaborne crude exports have plummeted from around 1.7 million bpd to nearly zero.
Oil flows throughout the Middle East have experienced an impressive recovery, with export volumes nearing pre-war levels, despite significantly lesser traffic through the Strait of Hormuz. Standard Chartered suggests that crude and condensate exports from the Gulf, excluding Iran, and encompassing bypass routes such as Fujairah and the Red Sea, reached approximately 16.5 million barrels per day (bpd) in September, akin to pre-war figures. However, only 60% of those barrels traversed the Strait of Hormuz, compared to 83% before the conflict. Standard Chartered argues that these statistics reflect resilience rather than full normalization: exporters have adapted to transport the oil but are operating less efficiently and incurring much higher costs.
This operational strain has necessitated increasingly intricate workarounds, including a vessel-heavy sequence of ship-to-ship (STS) transfers. Shuttle tankers are now often employed to move crude through Hormuz before transferring it to larger ships in the Gulf of Oman; additionally, there has been a heightened reliance on pipelines and ports that bypass the strait. The southern route along the Omani coast has emerged as a critical passage for shuttle vessels navigating through Hormuz. Standard Chartered observes that STS capacity appears maxed out, vessel efficiency is suboptimal, journey durations have increased, and both freight and security costs remain elevated.
Saudi Arabia exemplifies the dual success and limitations of these adaptive strategies. Following the early September damage to the East-West pipeline, there was a marked shift in exports towards the east coast. Standard Chartered estimates that total Saudi exports surged to around 6.9 million bpd in September from 2.45 million bpd in August, with 19 Very Large Crude Carriers (VLCCs) transiting Hormuz within a single week. The reactivation of the East-West pipeline and operations at Yanbu have restored another market access route, minimizing the immediate risk of production halts; however, the overall pipeline throughput remains beneath its maximum capacity and remains vulnerable to further attacks. The alternative logistics methods are proving costly, with reports indicating discounts of up to $9 per barrel on cargoes loaded off the coast of Oman to offset the additional logistical expenditures.
This increase in physical export volumes has lowered the chances of extreme shortages and should gradually alleviate some of the scarcity premium currently affecting oil prices. Even so, these barrels are being transported at higher costs, involving longer shipping durations, more frequent use of tankers, and reduced spare capacity within the logistics framework. Although Standard Chartered views this improvement as bearish compared to a market anticipating prolonged physical supply losses, it does not warrant a return to previous risk premiums. Exporters have shown they can move substantially more crude than anticipated, but the system has limited capacity to cope with another significant disruption.
The tactical success of Gulf exporters has also shifted regional dynamics. Iranian seaborne crude exports plummeted to nearly zero in September, down from approximately 1.7 million bpd prior to the conflict, as a result of a U.S. naval blockade severely limiting Tehran’s ability to transport crude via Hormuz. Consequently, Iran’s capacity to wield influence over oil exports through the Strait of Hormuz is diminishing, but this increases the risk of unpredictable military confrontations.
Iran has maintained a defiant stance, and recently reiterated that the Strait of Hormuz would remain closed until the United States fulfills seven conditions stipulated in the June interim agreement. Foreign Minister Abbas Araghchi stated that Tehran’s latest offer could lead to the strait’s reopening within a week if Washington complies with Iran’s demands.
Tehran has dismissed reports claiming it suggested international nuclear inspections in exchange for lifting sanctions. Araghchi has indicated that Iran hopes for U.S. diplomatic engagement but cautioned that the nation is better equipped than before to respond to further American military operations.