This week marks Naked Capitalism’s fundraising initiative. A total of 1,101 supporters have stepped forward to aid our mission of combating corruption and predatory practices, especially in the financial sector. We invite you to join us by visiting our donation page, where you can learn how to contribute via check, credit card, debit card, PayPal, Clover, or Wise. Explore our fundraising goals, what we’ve achieved this past year here, and how we aim to reward our talented writers.
Yves here. John Helmer recently highlighted a revealing report from JP Morgan’s investment team on the oil markets, where analysts candidly admitted that forecasting has become exceedingly difficult. This is an incredible admission from professionals who are well-compensated for their predictions.
Helmer astutely points out the analysts’ rationale. While they fail to confront the obvious disconnect—the disparity between the physical and paper oil markets exacerbated by Trump’s rhetoric and overly optimistic coverage from outlets like Bloomberg—they do note an often-overlooked issue: recessionary pressures are significantly impacting demand, challenging earlier expectations of soaring oil prices. There’s an old investor saying that captures this well: “High oil prices will cure high oil prices.”
In his analysis, Helmer takes a critical stance on the performance of Elvira Nabiullina, the head of Russia’s central bank, who has faced scrutiny for her orthodox approach that prioritizes inflation control over fostering economic growth. Critics argue that this has enabled Putin’s neoliberal policies. Nevertheless, it’s essential to recognize her role in stabilizing the economy during a crisis, particularly at the onset of the Special Military Operation, when she deftly navigated Russia’s economic challenges—a testament to the strength of Putin’s team.
Notably, Helmer highlights that Nabiullina has projected the potential for a significant recession in 2027, forecasting a GDP contraction of 8% to 10% among her four scenarios. It is perplexing that this alarming projection has not garnered more attention. Her baseline prediction indicates stagnation in 2026, with growth uncertain and limited to a maximum of 2.5% for 2027. Any growth exceeding 1% in that year would be a relative success, given the bleak outlook for global economic conditions.
By John Helmer, a veteran foreign correspondent in Russia and an independent journalist with no ties to national or commercial influences. Helmer has previously served as a political science professor and advisor to government leaders in Greece, the United States, and Asia. He is notably the first member of a US presidential administration (under Jimmy Carter) to establish residence in Russia. This piece originally appeared on Dances with Bears.
It’s noteworthy that JP Morgan, the largest bank in the U.S., finds common ground with the Central Bank of Russia (CBR) under Nabiullina regarding future trajectories and necessary actions for profitable navigation.
However, when JP Morgan’s commodities research team—comprised of three Russian émigrés—delivered their insights on global oil demand and supply, they conceded uncertainty in forecasting. Their professional euphemism, “we don’t have a baseline view,” illustrates a keen awareness of shifting dynamics. They reported that since the war with Iran began, Brent crude has averaged around $94, rather than the anticipated $130, while global crude inventories have decreased by about 555 million barrels—just one-third of earlier expectations. Demand is currently about 4.4 million barrels per day lower than it was a year ago. The market has adjusted through demand destruction as opposed to stockpiling, which usually signifies rising prices. China exemplifies this trend, with JP Morgan estimating gasoline demand in the region down by 180,000 barrels per day, of which 70% might not recover even after normalization, potentially reducing China’s crude import needs by a staggering 1 million barrels per day.
The bank warns that, despite fluctuations in energy flows through the Hormuz and Bab el Mandeb Straits, the U.S. conflict with Iran and the simultaneous confrontation with Russian oil tankers has already begun to erode global demand for crude oil and petroleum products. The immediate consequences indicate that oil prices are not destined to rise steadily, while individual countries’ GDP projections continue to spiral down into recession.
For American voters gearing up for the upcoming congressional elections on November 3, these concerns are particularly stark. The disapproval rating of the Trump Administration regarding inflation has soared to an all-time high of minus 42%, accompanied by significant dissatisfaction with its economic policies.
Contrary to JP Morgan’s uncertainty, Nabiullina firmly asserted in her September 30 report that she has a clear grasp of the situation. She presented four scenarios for the 2027-29 timeline: a risk scenario, a proinflationary scenario, a deflationary scenario, and a baseline scenario. Nabiullina expressed conviction that the baseline forecast would prevail, asserting, “The Bank of Russia considers the baseline scenario to be the most probable.” She added that while the risk scenario remains low, the proinflationary outlook appears more likely.
Should her baseline assumptions fail to materialize, Nabiullina emphasized that it wouldn’t be her fault but rather attributed to errors from the Ministry of Finance and external global influences. She noted that the fiscal policy assumptions underlying the baseline depend on indicators from the Ministry of Finance concerning the structural primary deficit of the federal budget, which the scenario anticipates will decrease gradually to zero by 2029.
Due to increasing defense expenditures linked to the war in Ukraine, Nabiullina implied her desire for a resolution to the conflict, aligning with U.S., European, and Ukrainian terms, thereby hinting at discord with military strategies advocated by Russian authorities.
In her risk scenario, she quietly acknowledged a grim possibility for the Russian economy, predicting a GDP contraction of 8% to 9% in 2027, accompanied by plummeting consumer spending and capital investment. Her baseline forecast for GDP this year hovers near zero, with next year’s growth capped at 2.5%. Nabiullina attributes expected supply shocks in 2026 to temporary production capacity constraints, which she defends as a transitory phenomenon, providing an excuse for reduced investments linked to her higher Central Bank interest rates.
As for external conditions, she suggests that current global economic trends and sanctions will largely remain unchanged. “Whatever the scenario may be,” she concluded, “the Bank of Russia’s monetary policy will aim to stabilize inflation at around 4% sustainably.” Such statements reflect a lack of confidence about what the future holds once her term concludes in June 2027.
The Kremlin-affiliated security analysis platform Vzglyad is now asserting that negative developments affecting adversarial states could ultimately benefit Russia’s military strategy. Ignoring JP Morgan’s narrative of demand destruction, Vzglyad claims, “The depletion of global oil reserves plays into Russia’s hands.”
In a speech at the Valdai Club, President Vladimir Putin offered a more measured assessment, noting that ongoing global conflicts are likely to continue, exacerbated by evolving dynamics that foster ambitious pursuits and risky endeavors for perceived high rewards. “I wish I were wrong,” he lamented, “but current trends suggest otherwise.”
The JP Morgan report underscores that accurately predicting future oil supply and demand has become increasingly elusive for analysts. “Anyone projecting a single average for 2027 oil and gas prices is choosing an optimistic timeline. Our estimated peace date is no longer a viable market indicator.”
Source: https://vz.ru/economy/2026/10/1/1457039.html Translation is verbatim; illustrations and captions have been added.
 October 1, 2026
The depletion of global oil reserves plays into Russia’s hands.
By Olga Samofalova
U.S. oil reserves have plummeted to their lowest point since 1982. The country has been actively tapping into these reserves to temper price increases. Without this strategy, oil prices would have surged even further. However, the final approved release from reserves has now been utilized. How will the U.S. navigate this dilemma?
Oil reserves in American storage have fallen to 284 million barrels, marking the lowest levels since 1982. The recent allocation allowed for the release of 172 million barrels as part of agreements with 30 countries within the International Energy Agency (IEA), which encompassed a global withdrawal total of 400 million barrels.
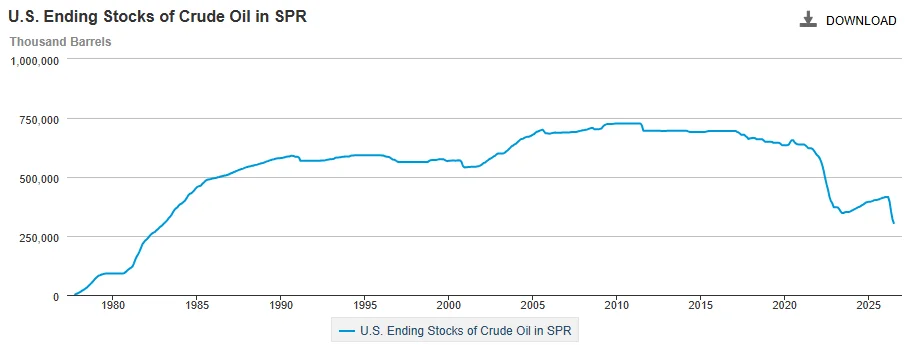
Source: https://www.eia.gov/dnav/pet/hist/LeafHandler.ashx?n=PET&s=MCSSTUS1&f=M Kpler reports that “around one third of 58 Mbbls of SPR releases have been exported. Cushing inventories approaching operationally low levels have tightened price spreads. As a result, US crude exports in June are expected to return to pre-conflict levels. Total US crude inventories have dipped by 86 Mbbls since late March, with continued draws projected for June despite reduced US crude exports.”
Meanwhile, the U.S. has voiced criticism towards European IEA member nations for contributing only a fraction of expected oil and petroleum products. The White House is urging the EU to deplete its emergency diesel fuel reserves to mitigate price hikes.
Complicating matters for the EU has been the realization that since the onset of the conflict between the United States and Iran, expenditures for fossil fuel imports have soared by an additional 100 billion euros, despite purchase volumes remaining unchanged. The fuel crisis is proving far more acute for the EU compared to the U.S., and Brussels faces fewer options to navigate through it.
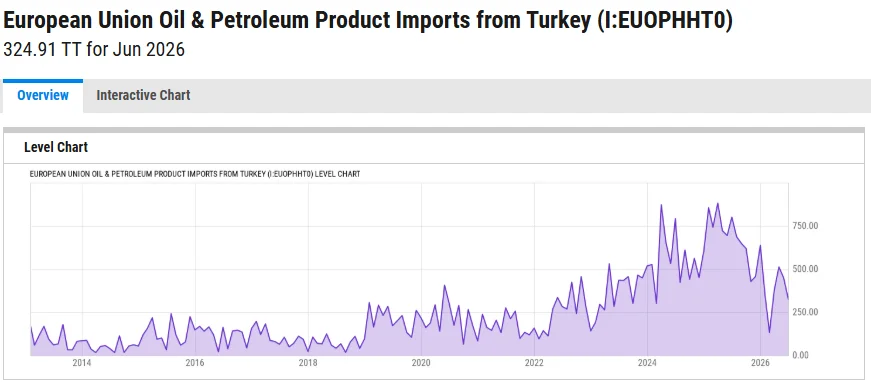
Furthermore, the EU has inadvertently exacerbated its predicament. Their ban on importing Russian petroleum products, established in 2023, along with restrictions on acquiring products made from Russian oil through third-party countries, has curtailed their fuel supplies from nations like Turkey and India, resulting in escalated gasoline and diesel prices.
Source: https://ycharts.com/indicators/european_union_oil_and_petroleum_product_imports_from_turkey
The strategic release of oil reserves has certainly tempers the rise in local oil prices. However, at the onset of conflict in the Middle East, oil stored on tankers, including from Russian and Iranian sources, was being consumed rapidly. Currently, almost 100 million barrels of Russian oil remained offshore India. Recently, the strategic reserves from the U.S. and European nations have been more actively utilized. However, these reserves are finite; the U.S. currently holds only 284 million barrels, and experts suggest that 200 million is the operational minimum to avoid compromising strategic reserve functionality. Consequently, the actual remaining amount in reserves is considerably less than it appears, according to Igor Yushkov, an analyst at the National Energy Security Fund. He warns that without these strategic withdrawals, the pressure would significantly escalate, resulting in much higher oil prices.
What other strategies can the U.S. pursue to alleviate the price pressures that are affecting Donald Trump’s standing at home?
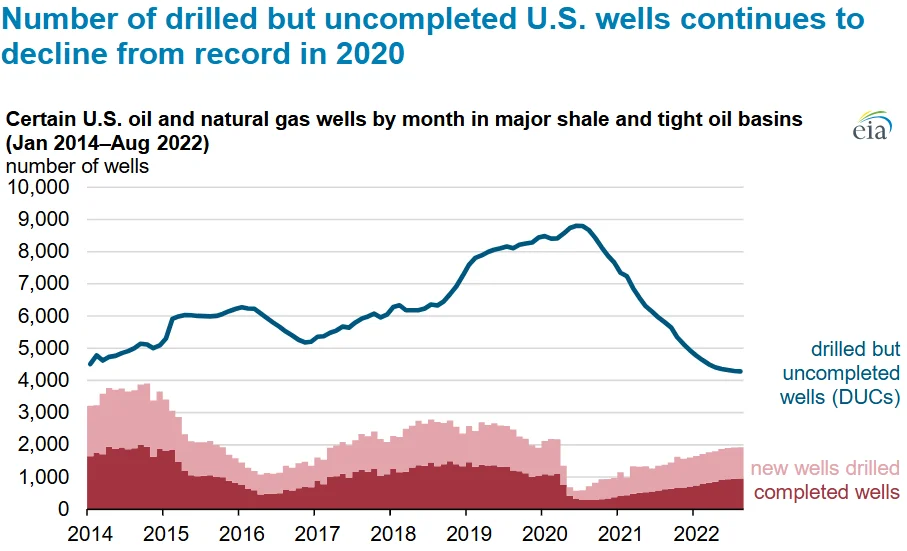
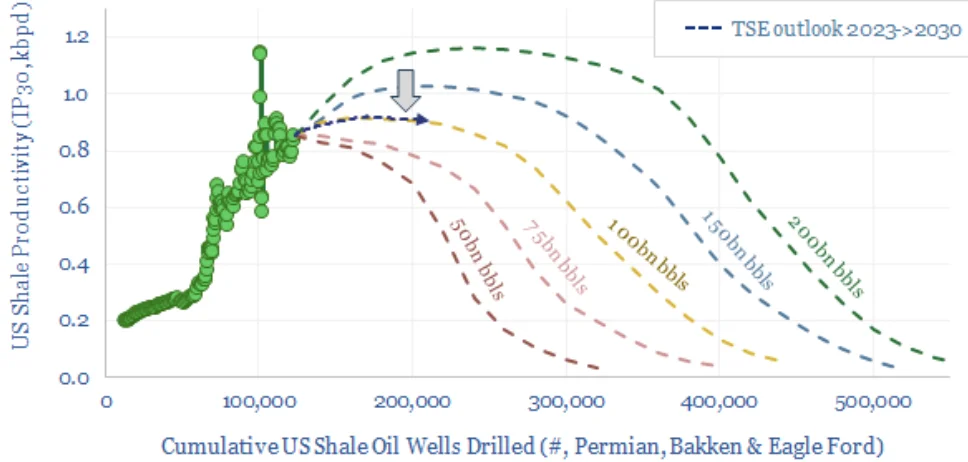
“First, as prices continue to climb, a growing number of new projects in the U.S. will become economically viable. Unlike conventional oil deposits in countries like Brazil, U.S. shale oil production is highly responsive and can ramp up swiftly. If prices increase significantly, American producers will be able to expand their output rapidly,” Yushkov explains.
Source: https://www.eia.gov/todayinenergy/detail.php?id=54179
Source: https://thundersaidenergy.com/2023/09/14/shale-oil-fractured-forecasts/
Moreover, the U.S. could seek to resolve the crisis with Iran by negotiating a ceasefire and reopening the Strait of Hormuz.
“Another possibility includes the U.S. launching strikes against Houthi forces to protect the East-West oil pipeline and ensuring Saudi Arabia’s oil exports via the Red Sea,” the FNEB expert elaborates. In summary, a variety of strategies could be employed concerning Middle Eastern dynamics, including potentially easing certain anti-Russian sanctions to enable increased Russian oil production and exports.
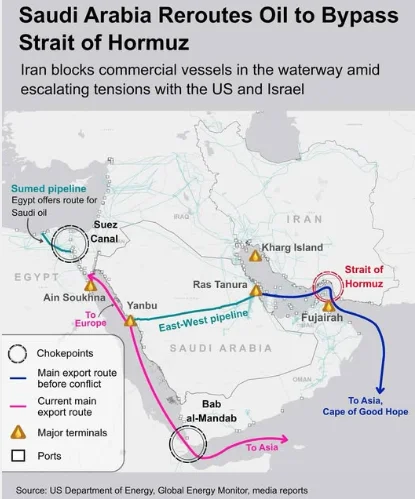
For the U.S., scaling up production in Venezuela poses significant challenges, necessitating a staggering $100 billion investment merely to increase output by 1.5 million barrels per day by 2030. In the current crisis context, Venezuela is unlikely to provide any relief.
Another option being explored by the U.S. involves increasing oil supplies through European channels. This rationalizes Washington’s pressure on European nations to utilize their strategic reserves more actively, even though their volumes are considerably limited. “Ultimately, this could lead to the sale of additional U.S. oil to European nations seeking to replenish their reserves, further solidifying their reliance on American exports. Therefore, depletion of Europe’s strategic oil reserves ultimately serves U.S. interests,” Yushkov concludes.
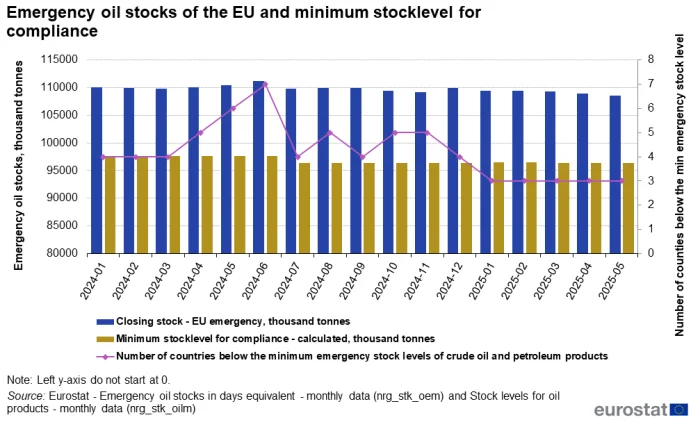
Source: https://ec.europa.eu/eurostat/statistics-explained/index.php?title=Emergency_oil_stocks_statistics
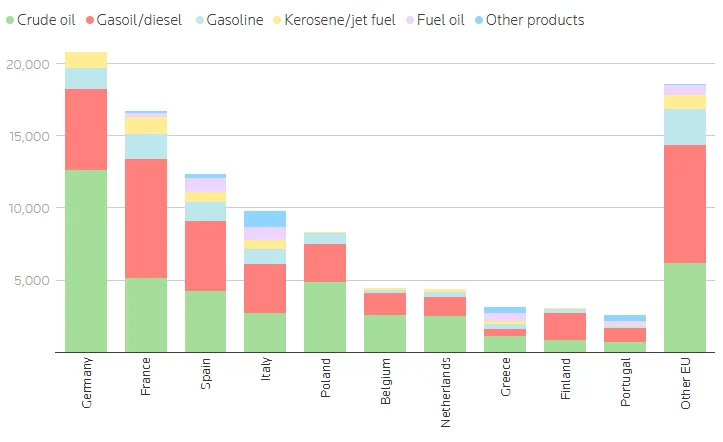
The ongoing depletion of strategic oil reserves will play a significant role in maintaining elevated oil prices, even following any potential peace agreements and the reopening of the Strait of Hormuz.
“The quantities withdrawn from strategic reserve facilities will require replenishment. Demand for oil will remain high not only for current needs but also to restock those reserves. The unfolding crisis underscores the reality that similar situations could arise in the future. As a result, nations with established strategic reserves are likely to invest not just in replenishing but also in expanding their reserves; for instance, China’s reserves stand at 1.4 billion barrels. Countries lacking these reserves will strive to build them up. Consequently, high oil demand is expected to persist for an extended period. By 2027, the process of restocking strategic reserves may significantly contribute to elevated global prices,” the source concludes.
In summary, the depletion of strategic reserves in consumer nations presents a long-term advantage for oil importers, including Russia.