This week marks a significant fundraising effort for Naked Capitalism. As of now, 980 donors have contributed to our mission to fight corruption and exploitative practices, especially within the financial sector. We warmly invite you to support our cause through our donation page, which provides options for contributions via check, credit card, debit card, PayPal, Clover, or Wise. To learn more about the reasons behind this fundraiser, check out why we’re asking for your support, what we’ve achieved over the past year, and our current goal: providing bonuses for our amazing writers.
Argentina’s Economic Turmoil: A Shift in Tone from Wall Street
“Argentina suffered its most severe monthly decline since the April 2020 lockdown, with the activity indicator falling 2.9% month-on-month.”
JP Morgan Chase exerts considerable influence over the Argentine economy, perhaps more than any other financial institution. Currently, six senior positions in President Javier Milei’s government are occupied by former JP Morgan employees. Notable figures include Minister of Economy Luis Caputo and Foreign Minister Pablo Quirno, alongside key roles in the Central Bank and the Ministry of Economy.
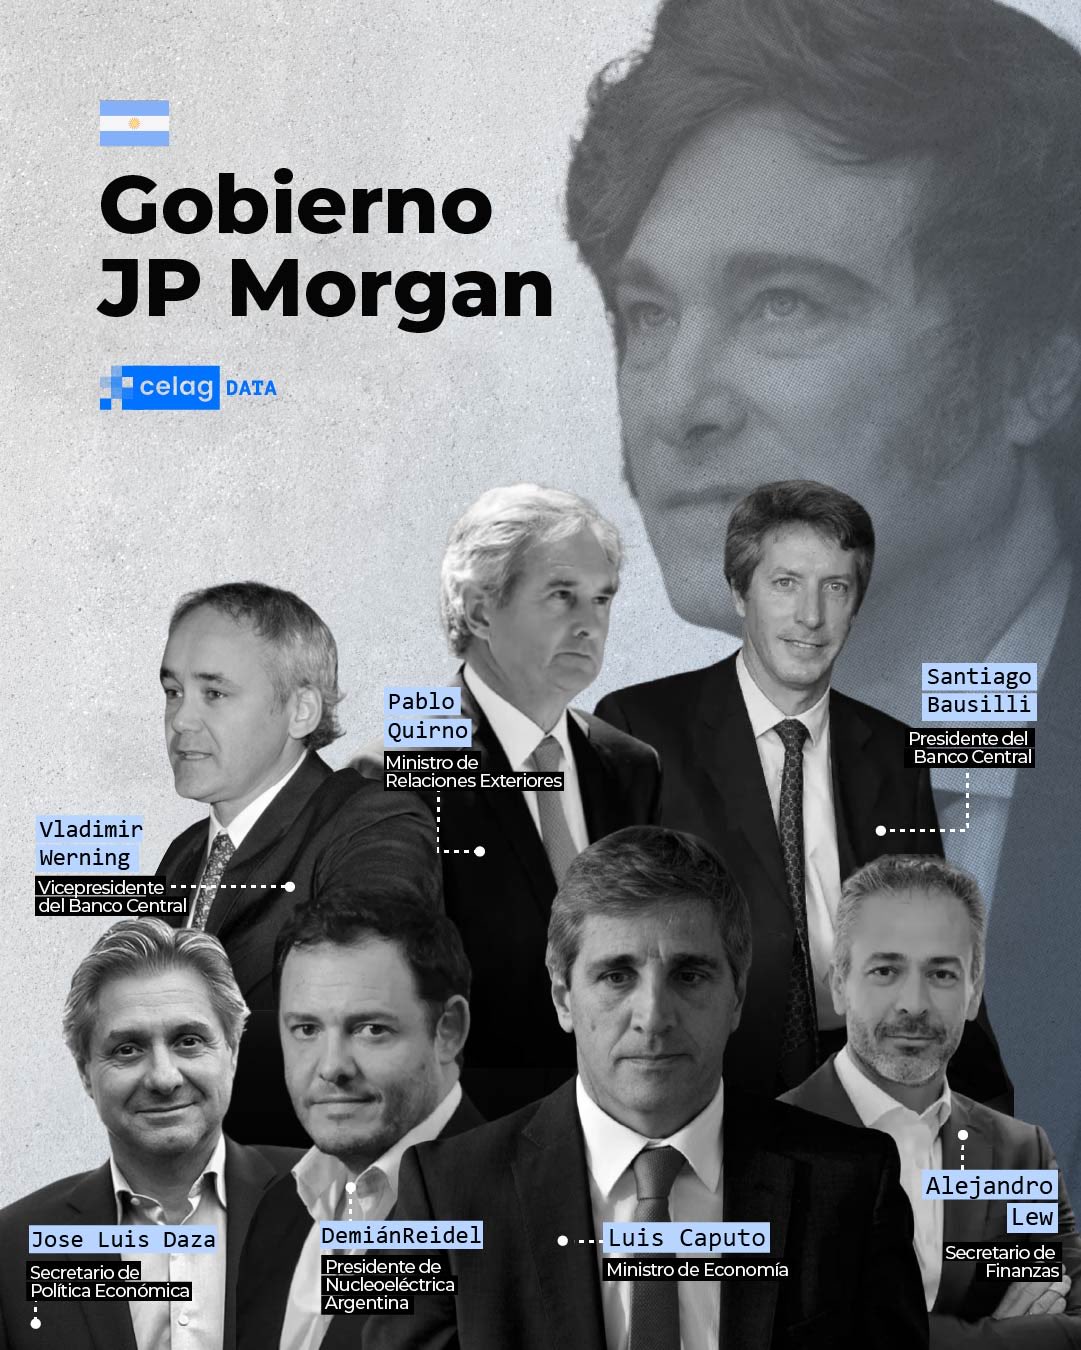
Such a presence typically equates to significant influence. JP Morgan has long supported Milei’s economic agenda. CEO Jamie Dimon has made several trips to Argentina, and in October 2025, he visited alongside prominent figures like Tony Blair and Condoleezza Rice, who are part of JP Morgan’s International Council.
During those visits, Dimon reportedly met with key members of Milei’s economic team, likely receiving a warm reception given their shared JP Morgan background.
Argentina’s right-wing libertarian government is effectively managed by Wall Street, both directly and indirectly.
President Javier Milei’s ministerial team includes several former JPMorgan executives. https://t.co/k9yqKikxge
— Ben Norton (@BenjaminNorton) October 21, 2025
In March, JP Morgan agreed to host its annual Argentina Week at its New York headquarters to promote foreign investment. Dimon even delivered the opening speech. Thus, it came as a surprise when President Milei and his team reviewed a disheartening report on Argentina’s economy from JP Morgan just days ago. Its opening lines set an alarming tone:
We anticipated a weak activity report for July, consistent with the lackluster performance in Q2. However, the contraction substantially exceeded our estimate of approximately -1%. Argentina recorded its worst monthly performance since the April 2020 lockdown, with a 2.9% month-on-month decline and a 1.4% drop compared to July 2025. Excluding past crises, July 2026 marks the largest decline since 2008.
The preliminary data for July follows a 0.6% contraction in Q2 2026, indicating Argentina is on the verge of a technical recession—its ninth such occurrence in 32 years. Economists consulted by Bloomberg assert that a growth of about 6% from August to September would be necessary to avert this fate, a scenario that seems highly improbable.
Interestingly, just prior to this negative outlook, JP Morgan analysts had speculated that Argentina could be approaching an investment-grade rating, which would facilitate foreign investment. However, the publication of the national economic data for July drastically altered that sentiment.
The bank also highlighted the concerning job landscape in Argentina. Many thriving sectors under Milei’s exploitative economic model, such as agribusiness and mining, are not labor-intensive, while sectors that are, like manufacturing and retail, are either stagnating or contracting.
As a result, formal employment stands 3.9% below the 2016-2019 average, with significant declines in manufacturing and construction. The growth of low-quality self-employment remains a troubling trend, which JP Morgan suggests is indicative of a structural rather than cyclical issue.
Another alarming statistic is Argentina’s rising country risk index, which measures investor confidence in national sovereign debt. This index has surged over 50% in the past two months and currently sits above 600 basis points, its highest in five months. Although this remains far below the level when Milei took office, such spikes signal increased borrowing costs for both the government and private companies.
As the index rises, investors perceive a greater likelihood of financial instability, debt restructuring, or political upheaval. A significant economic slowdown or recession could exacerbate these challenges, especially with elections looming just a year away.
A recession that leads to reduced economic activity, job losses, and wage declines will not bode well for Milei’s re-election prospects in November 2027. While falling economic activity could potentially enhance external balances, what concerns investors is the possible impact on the 2026 electoral outcome.
Additionally, Argentina’s rising country risk may also stem from deteriorating global economic conditions. Although emerging markets have shown resilience to recent shocks, it’s only a matter of time before they too feel pressure as soaring US yields lead investors towards better-quality issuers.
In such a scenario, Argentina is at significant risk. A recent report from the Inter-American Development Bank ranks Argentina as the most vulnerable country in Latin America, scoring a striking 80 points—almost double that of the Dominican Republic, which is in second place.
With Wall Street banks now cautioning against the risks faced by Argentina’s economy, the narrative has shifted dramatically. Less than a year ago, a consortium of US banks, including JP Morgan, reportedly contributed $20 billion to Argentina’s pre-election bailout fund, purportedly to aid Milei’s electoral chances during mid-term elections. However, subsequent revelations suggested that this fund was more illusion than reality.
Wall Street Banks Come to the “Rescue” of Milei’s Argentina Just Days Before Make-or-Break Elections https://t.co/e1H8vsobKg
— Yves Smith (@yvessmith) October 24, 2025
It’s not only Wall Street banks that are reassessing their stance on Argentina. Financial news outlets, both in English and Spanish, are beginning to pose critical questions concerning the sustainability of Milei’s aggressive economic strategy. Spain’s El Economista, which had been among Milei’s staunchest supporters, now suggests that the initial successes of Milei’s project may have created heightened expectations among analysts and the public:
Javier Milei’s economic experiment is encountering difficulties. The economy is contracting, raising the risk of a technical recession (two consecutive quarters of GDP declines), and one of the previously bright indicators—the poverty rate—is now worsening. The initial enthusiastic results observed in late 2024 spurred euphoria among analysts and the media.
However, stringent measures to combat inflation, including high interest rates and cuts in public spending, are leading to significant economic obstacles. If the economy deflates, Milei’s electoral prospects fade, which is already reflected in the rising country risk, surpassing 600 basis points after recently declining to 400.
As a result, JP Morgan has revised its forecasts downward and reduced its growth estimate for the Argentine economy in 2026 from 2.7% to 1.5%. The bank anticipates a 4% contraction in the third quarter, following the decline in Q2.
Moreover, the report indicates that urban employment barely changed in July after five consecutive months of losses, reflecting a 1.1% decrease compared to the previous year and limiting hopes for a quick recovery in household consumption. Mining and energy export sectors, central to Milei’s extractive model, generate few domestic jobs.
The Wall Street Journal has also begun to reevaluate its tone regarding Milei. A June article warned that Milei’s contentious social-media persona, which aided his campaign, is now alienating allies and diminishing public support:
“He’s a creature of the internet, his persona was built online,” says Benjamin Gedan, director of the Stimson Center’s Latin America Program. “Milei’s combative nature on X reflects the traits that hinder his ability to build lasting coalitions and win over moderates.”
Currently, Milei’s approval ratings have plummeted to their lowest since he took office. His chief of staff faces allegations of illicit enrichment, and public dissatisfaction with economic conditions remains high. Even with inflation slowing, many Argentines struggle financially, leading to increasing fatigue with Milei’s confrontational style.
In response to criticism, Milei contended that much of the official economic data is inaccurate, a claim that could have some merit—though likely favoring the government. He asserted in a recent interview that “the economy has been growing for 27 or 28 consecutive months,” contradicting official reports, which indicate that the economy did not recover from a serious recession until late 2024.
Milei also downplayed the July economic collapse, with Economy Minister Caputo attributing part of the downturn to people taking time off to watch the FIFA World Cup. Caputo even suggested that investor hesitance stemmed from fears of a potential return of “Kirchnerismo,” the left-leaning opposition.
This narrative has become a familiar refrain in Argentina. Financial analyst Carlos Masláton notes that this isn’t the first time JP Morgan has terminated support for an unsustainable economic model:
JP Morgan, is this a joke? They have been praising Caputo and Milei’s plans for three years, despite knowing that the overvalued exchange rate—sustained by interest and credit—cannot hold and will inevitably collapse. Now they claim to be disappointed?
It’s always the same with JP Morgan… While I understand how the international financial system operates, countless naive individuals believe them when they claim everything is fine.
As noted by others, the bank likely got what it aimed for. After nearly three years of Milei’s economic approach, prioritizing speculatory profits over the real economy, financial speculators profited significantly, but that gravy train may soon run dry.
Economist Saifedean Ammous explains how the so-called “financial bicycle” has become Argentina’s dominant industry and why it’s unsustainable:
Since Milei’s inauguration in December 2023, he reneged on his promise to close the central bank and allowed the peso to depreciate against the dollar at a controlled rate. By April 2025, this measure was abandoned, and bonds were offered at unsustainably high interest rates, creating an arbitrage opportunity. Those investing can earn returns exceeding currency devaluation, so long as they have dollar savings. However, this scheme is naturally unsustainable; as bond yields rise, the peso depreciates further, eventually leading to a collapse. At that point, investors will flee, resulting in a currency collapse and force the government to seek an IMF bailout.
Former JP Morgan banker and current Economy Minister Luis “Toto” Caputo is termed “the architect of the financial bicycle,” as noted by Masláton.
One crucial difference between the current scenario and 2018 is the Milei administration’s attempts to eliminate restrictions on foreign ownership of Argentine land. This effort received a boost recently when the Argentine Supreme Court reinstated Milei’s decree that removes long-standing limitations on foreign purchases.
Legal expert Andrés Gil Domínguez expressed concerns that this ruling allows any foreign entity to buy rural land without restriction, including in border areas. Thus, in the event of another economic collapse, Argentina’s assets may be sold off cheaply.
When asked whether a foreign investor could buy an entire village or province, Foreign Minister Quirno stated, “yes, that will produce benefits for Argentina.”

In conclusion, Argentina faces a complex economic situation marked by disillusionment among major financial institutions and a rising country risk index. The Milei government’s aggressive economic model is under scrutiny, signaling a precarious future for both the country and its leadership. As the nation grapples with potential recession and societal unrest, the path forward remains unclear, with pressing implications for both domestic and international stakeholders.