UK Investment in EV Battery Manufacturing
The UK government has announced a substantial investment of £7 billion (approximately US$9.3 billion) aimed at bolstering its electric vehicle (EV) battery manufacturing and recycling capabilities. Despite this investment, a notable supply gap of 55 GWh is projected by 2035.
Key Findings from Recent Report
According to a recent report by New AutoMotive titled “The UK’s EV Battery Economy,” the demand for EVs is growing rapidly. In August alone, Battery Electric Vehicles (BEVs) made up 30% of new car registrations, marking a record high.
Policy Support Driving Growth
Supportive policies, particularly the Zero-Emission Vehicle (ZEV) Mandate that goes into effect in January 2024, are essential in driving the growth of battery manufacturing. This mandate requires manufacturers to increase the proportion of zero-emission vehicles they sell.
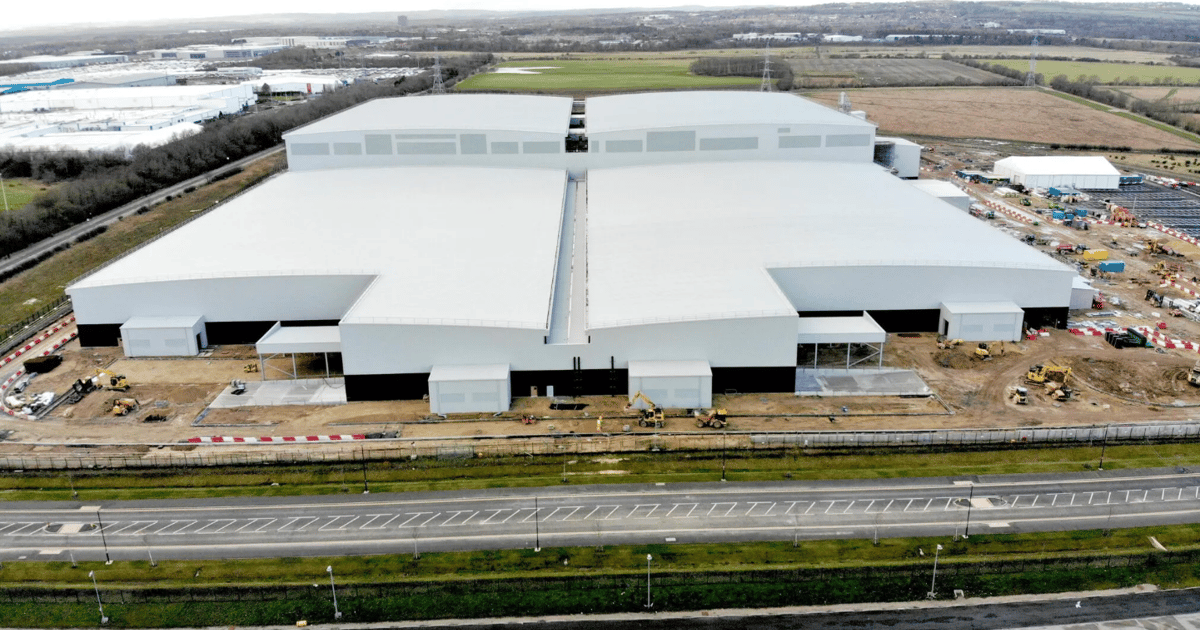
The ZEV Mandate has already catalyzed over £41 billion in new automotive investments, as it not only governs domestic sales but also encourages exports. The establishment of significant manufacturing projects, such as Agratas’ 40 GWh facility, indicates growing optimism within the sector.
Domestic Resource Development
The UK’s mining sector is also strengthening, with projects like Cornish Lithium and Aberdeen Minerals securing over £53 million in funding to establish domestic mining operations. This effort aims to provide essential minerals for EV battery production.
Recycling and Future Prospects
The report highlights recycling as a unique strength for the UK EV market. Since UK EVs are likely to be recycled domestically, they can serve as a consistent source of materials for new battery production. The report emphasizes the need for continued government support, especially through the ZEV Mandate.
Ongoing Challenges
Despite the potential for growth, the UK is at an “early” stage in battery manufacturing and will need significant expansion to meet future demands. Current manufacturing capabilities, primarily at AESC’s 15.8 GWh facility and Agratas’ upcoming plant, fall significantly short of the projected need for 115 GWh by 2035.
The dominance of China in the global battery supply chain poses additional challenges. China produces over 98% of LFP cathodes and approximately 90% of battery cells, creating intense competition for the UK as it seeks to establish its own battery manufacturing capabilities.
Policy Recommendations
The report urges the UK government to maintain a clear demand signal to attract investors. Stable, long-term policies like the ZEV Mandate are crucial for developing a robust EV manufacturing ecosystem. Additionally, it suggests that the UK could benefit from adopting some policies from the EU, especially those related to battery design and material traceability.
In conclusion, while there are promising developments in the UK’s EV battery sector, significant challenges remain. Robust policy support and strategic investments will be essential to meeting future demand and establishing the UK as a leader in EV production.