This week marks the fundraising initiative for Naked Capitalism. Already, 241 supporters have contributed to our mission to expose corruption and combat predatory practices, especially within the financial sector. We invite you to join us in this effort by visiting our donation page, where you can choose to donate via check, credit card, debit card, PayPal, Clover, or Wise. To learn more about the purpose of this fundraiser, what we’ve achieved over the past year, and our current goal of supporting our community of commentators, please have a look.
Yves here. This article demonstrates that inflation rates in advanced economies have historically exhibited synchronized movements, challenging the assumption that domestic factors are the primary influences. While some may cite instances of hyperinflation as exceptions, these too align with the theory that “no country is responsible for its own inflation.”
Hyperinflation stems from a significant loss of productive capacity rather than simple excessive government spending or supply shocks. For example, the hyperinflation in Weimar Germany was triggered by harsh reparations imposed after World War I. John Maynard Keynes, a key member of the UK Treasury involved in structuring these reparations, resigned in protest, writing the influential book, *The Economic Consequences of the Peace*, to explain how damaging these reparations would be for Germany. When Germany struggled to pay the required amount in gold marks, or to provide sufficient supplies of in-kind goods such as “coal, timber, chemical dyes, pharmaceuticals, livestock, agricultural machinery, construction materials, and factory machinery,” France responded by occupying the Ruhr Valley, a crucial coal and steel production region.
Similarly, Ukraine appears poised for hyperinflation due to its loss of the Donbass region, akin to the Ruhr, along with the disruption of grain exports resulting from Russia’s blockade of Odessa and much of the Black Sea coastline.
By Carlo D’Ippoliti, Professor of Economics, Sapienza University of Rome; Daniele Tori, Assistant Professor of Political Economy, University of Pisa; and Lucio Gobbi, Assistant Professor of Economics, University of Trento. Originally published at the Institute of New Economic Thinking website
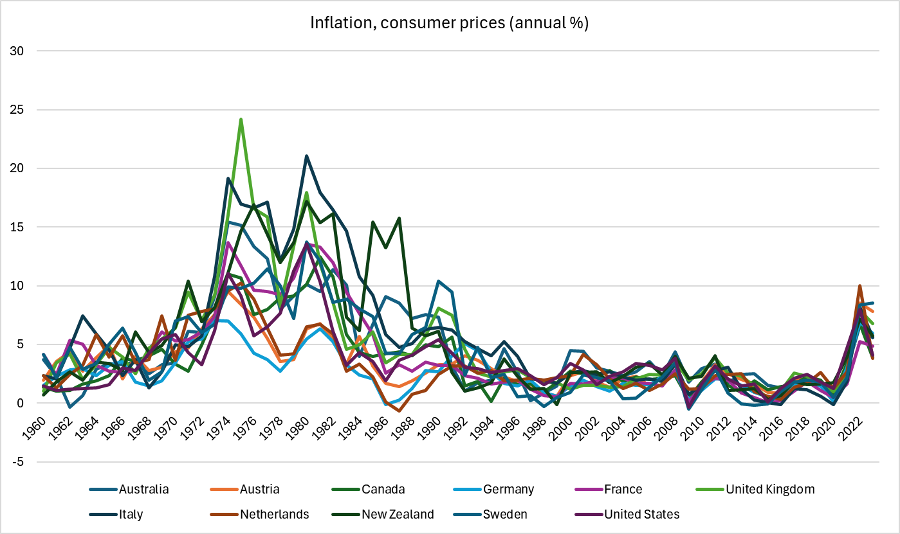
When you consult an economist regarding the origins of inflation, responses often revolve around national factors: labor markets, fiscal policies, or central banking. Yet, a closer look at the data reveals a different narrative. Figure 1 illustrates consumer price inflation across eleven advanced economies over more than sixty years, resembling a unified trend replicated across countries. The inflationary surge of the 1970s, the quiet period following 1990, and the spikes of 2021 and subsequent retreat occurred simultaneously for all nations, regardless of their individual policies or governance.
Figure 1. Consumer price inflation, selected advanced economies, 1960–2023 (annual %).
Source: World Bank data; Figure 1 of the working paper.
The typical response to this phenomenon involves attributing it to a common shock. Events like the oil crisis of 1973, the pandemic, or the conflict in 2021 impacted all economies simultaneously, leading inflation rates to rise in unison. Such shocks are undeniable and significant; anyone who lived through the energy price volatility of 2022 in Europe can attest to that. However, this alignment of inflation rates predates the pandemic and persisted through tranquil periods devoid of crises. Relying on a new explanation for each inflationary episode feels less like a unified theory and more like a convenient excuse.
In our recent INET Working Paper, we suggest that the real issue lies in the methodological nationalism that permeates inflation theory. Current frameworks—monetarist, Keynesian, or conflict-based—depend on a domestic narrative occasionally disrupted by external shocks. Even those perspectives that attempt to adopt a global approach still tend to view the international economy as a disturbance impacting national systems. Conversely, the “globe-centric” perspective from the Bank for International Settlements aims to establish global Phillips curves, asserting that global slack influences local prices, yet it overlooks the interactions among countries.
We propose to examine inflation as a result of interaction among open economies, deeming it an interconnected global phenomenon rather than a mere aggregation of national experiences. The framework is straightforward: shocks and structural transitions influence relative prices. Whether these translate into sustained inflation depends on the power dynamics between stakeholders—workers, firms, debtors, creditors, and deficit versus surplus nations. This distribution of power is inherently international. Our paper outlines three key mechanisms, each relevant to traditional inflation theory (see table).
The three mechanisms discussed in the working paper.
| As a domestic story | Recast internationally | |
| Labor market | Wages and bargaining power set costs | Capital mobility and value chains reshape bargaining power globally |
| Real market | Demand and supply influence prices | Surplus nations stabilize prices, limiting inflation elsewhere |
| Money and finance | Monetary policy regulates liquidity | Global liquidity affects commodity and asset prices across borders |
The labor market has evolved due to global value chains and free capital movement, altering negotiation dynamics. The threat of relocation is a credible concern for companies and has significantly weakened labor’s ability to secure real wages, particularly in advanced economies. Our findings indicate a strong correlation between openness to capital flows and lower inflation across nations, while the influence of union strength appears less consistent. Ultimately, it is international capital mobility, rather than domestic labor power, that shapes the possibilities for wage-induced inflation.
In the realm of finance, global financial cycles influence credit availability, asset valuations, and risk tolerance across nations simultaneously. Commodity markets are especially affected as oil, gas, and food not only serve as essential inputs but are also traded extensively in financial markets; thus, their pricing is determined by financial instruments before physical transactions occur. In times of abundant global liquidity, especially when it flows through non-bank intermediaries rather than traditional banks, its impact can permeate the cost structures of economies regardless of local demand pressures. Our paper illustrates the correlation of global liquidity and financial activities with energy and food price indices over the past twenty years.
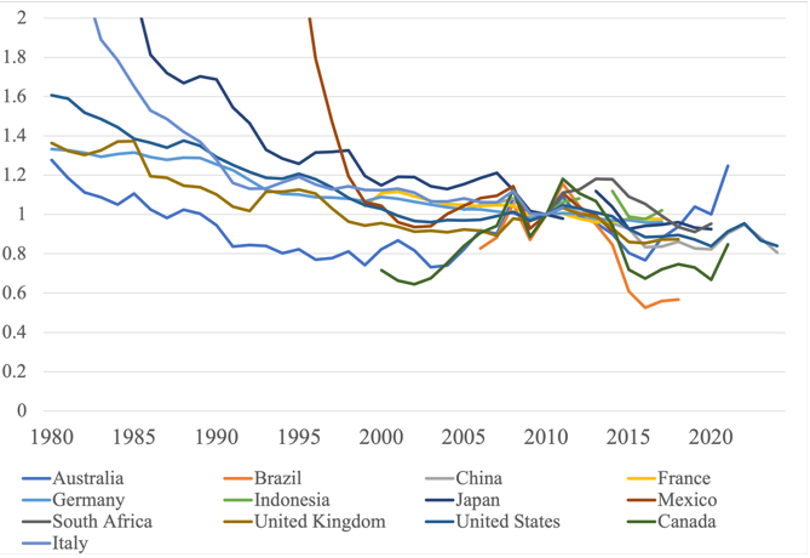
The third mechanism relates to the real market. Conventional wisdom posits that flexible exchange rates insulate nations from inflation differentials. Empirical data contradict this notion; real effective exchange rates have remained relatively stable. Figure 2 illustrates that export prices have historically increased at a slower rate than consumer prices among major economies. We posit that the prices of tradable goods are anchored by a select group of persistent surplus nations (notably Germany, Japan, and China), which uphold competitiveness, thereby constraining international prices and, by extension, inflation for other countries. Nations with trade deficits cannot adjust through deflation, as nominal prices tend to resist declines; rather, they experience adjustment through shifts in income and output. Consequently, this engenders a structural deflationary bias in the global economy, echoing the concerns Keynes advocated for during the Bretton Woods Conference with his proposal for an International Clearing Union. Central bankers have often claimed credit for achieving stability, which in reality is largely structural. When the pandemic prompted these anchor nations to engage in fiscal expansion and elevate wage growth, the constraining ceiling lifted, resulting in a resurgence of global inflation.
Figure 2. Ratio of the export price index to the consumer price index, selected economies, 1980–2022. A declining ratio signifies that export prices are rising more slowly than consumer prices.
Source: Figure 3, panel (b), of the working paper.
We present these ideas not as definitive conclusions but as a guiding framework for future research. The empirical challenges are significant; under standard analytical methods, a scenario with common shocks often mirrors a scenario of interdependent economies because the time effects capturing inflation’s common component can mask their differences. Distinguishing between these scenarios will require analyzing how differently affected nations respond, which is something a mere common shock cannot account for. The paper articulates various hypotheses and criteria for assessing their validity. The most apparent test revolves around the anchors: if Germany, Japan, and China revert to their historically low inflation rates, thus reinstating a cap on global inflation, our interpretation gains validity; if global inflation aligns solely with common shocks, irrespective of their current policies, our perspective diminishes.
The implications of these insights extend beyond mere scholarly debate. If inflation results from interactions between nations as well as from domestic variables, then tools designed for unilateral implementation may be fundamentally flawed. The recurring scenario of synchronizing central banks tightening their policies, each acting to defend its own currency, is rational at an individual level yet ineffective on a collective scale. This pattern also applies to commodity markets, where no single importer possesses the power to regulate prices set globally, along with the consequent burden of adjustment that falls primarily on countries with trade deficits. What is sorely needed is enhanced coordination among nations: concerning monetary policy, regulation of commodity and financial markets, and the equitable distribution of adjustment costs. The underlying issue lies more in the structure of global economic rules than in the actions of any one country. For fifty years, the focus has been on what each country individually does to its prices. It is now time to shift our inquiry to what countries collectively do to each other’s economies and how they can collaborate for mutual benefit.