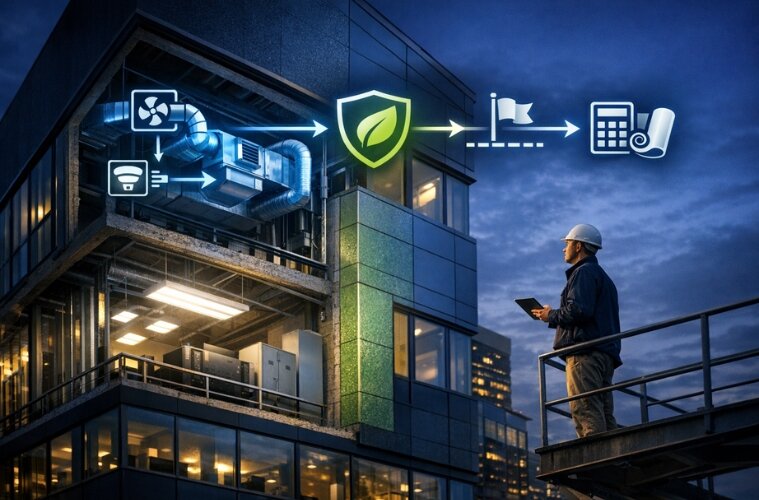
The landscape for building retrofits is shifting, especially regarding the federal Section 179D deduction, which will not be available after June 30, 2026, for construction that starts after this date. This change has important implications for projects in the 2027 budget cycle.
Key Takeaways:
-
Eligibility Deadline: Any construction commencing after June 30, 2026, will not be eligible for the Section 179D deduction. This includes retrofits, even if they wrap up in 2027.
-
Deduction Overview: Section 179D enables owners to deduct part of the costs for energy efficiency upgrades to commercial buildings, contingent on meeting certain energy savings criteria—typically a 25% reduction.
-
Documentation Importance: Documentation surrounding the construction start date and project scope will be critical for determining eligibility for the tax deduction. This includes detailed records of construction and energy modeling.
-
Public Buildings Not Exempt: The change applies equally to government buildings, with allocations typically going to the project’s designer.
-
Tax Implications: The deduction is not a dollar-for-dollar reduction in tax owed and varies based on tax rates. Owners must reevaluate their financial models to avoid overstating benefits.
-
Rethinking Retrofit Strategy: Moving forward, the focus should shift towards energy savings, equipment reliability, and maintenance costs rather than tax deductions.
-
Utility Incentives and Energy Contracts: Exploring incentives from utility companies and employing energy performance contracts could provide financial relief and ensure energy savings.
-
Future Projections: As the Section 179D deduction ends for new construction starts, efficiency projects will need a solid operational rationale without relying on previous federal incentives.
For a successful 2027 budget, building owners should seek to clarify eligibility for the Section 179D deduction, ensure accurate financial modeling, and prioritize retrofits that provide tangible operational benefits.