Caterpillar Inc. (NYSE: CAT): A Strong Business, But Is It a Good Buy?
Caterpillar Inc. is demonstrating robust financial performance, characterized by strong construction and mining demand, significant infrastructure investments, and emerging opportunities in data centers. Recently, the company reported record sales of $20.5 billion, marking a 24% increase year-over-year, while its adjusted EPS surged 73% to $8.17.
Competitive Advantage
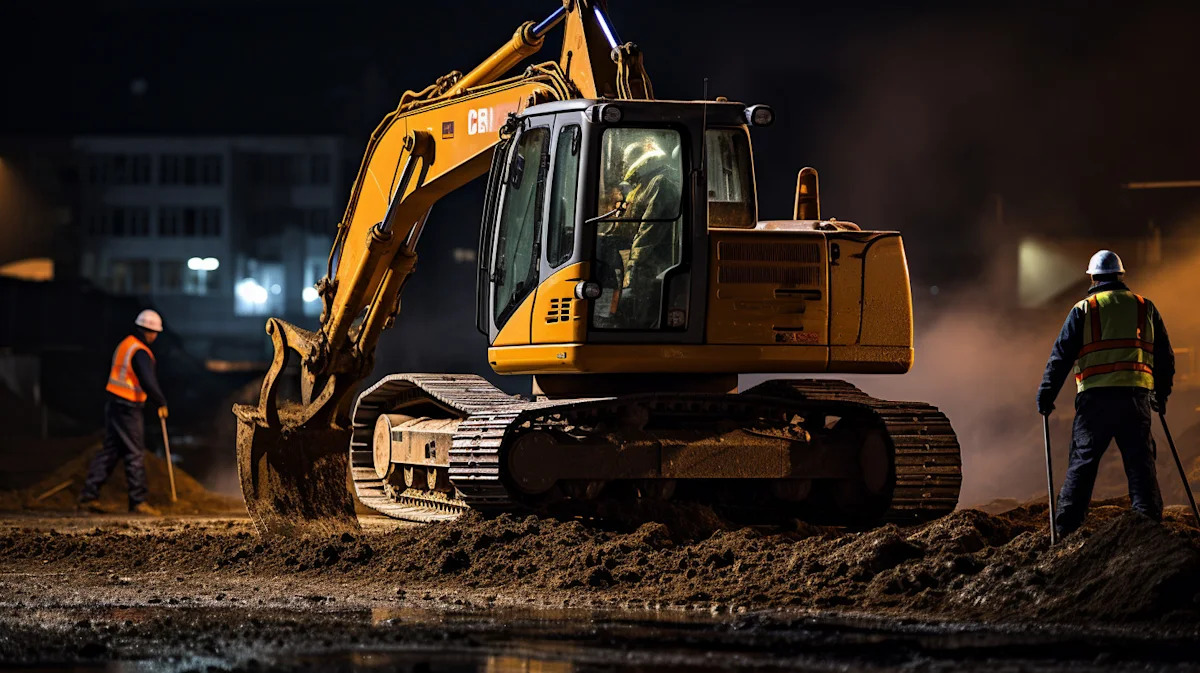
Most people associate Caterpillar with its iconic yellow construction equipment, but its competitive edge extends beyond products to include a well-established dealer network, robust service support, and a dependable parts supply chain. This relationship fosters customer loyalty, making it costly and complicated for clients to switch to competitors. Recent revenue growth reflected this competitive moat, with Construction Industries up 35% and Power & Energy rising 17%, bolstered by growing demand from data centers.
Valuation Overview
At first glance, Caterpillar’s valuation might appear steep, with a trailing P/E ratio around 35x and forward P/E at 25.4x. However, given the impressive earnings growth—adjusted EPS rising from $4.72 to $8.17—it suggests that these numbers alone offer an incomplete picture. Caterpillar’s forward P/E, while still above average, looks more reasonable given current earnings trends.
Cash Flow
The company’s cash flow is another highlight of its investment narrative. In the second quarter, Caterpillar generated $4.4 billion in operating cash flow and returned $2.2 billion to shareholders through share buybacks and dividends. This healthy cash generation offers a strong foundation for future growth, although this creates higher expectations for sustained performance.
Risks Ahead
Despite its positive outlook, Caterpillar remains a cyclical company vulnerable to rapidly changing economic conditions, which could affect construction and mining demand. If earnings growth were to slow, the current premium valuation would become challenging to defend, leading to potential downward pressure on the stock.
Conclusion
Caterpillar is a formidable player in its industry, boasting significant competitive advantages and a strong growth trajectory. However, its current valuation suggests limited room for error. For existing shareholders, it may be wise to hold, while new investors might wait for a better entry point or further earnings growth to justify the high valuation.
For those exploring alternatives, certain AI stocks are highlighting potential higher returns with reduced risk. If you’re interested in this area, consider reviewing reports on promising AI investments.